
Turning 65 or leaving work coverage

New to Medicare in Arizona: Your First Steps

Medicare has a lot of moving parts, and nobody hands you a map. Here is the order to do things in, who handles each step, and where our Chandler team helps, at no cost to you.

Key points

  • You sign up for Part A and Part B through Social Security.
  • A Medigap plan, a Medicare Advantage plan or a Part D drug plan is chosen through a licensed agent like Rise Up, or directly with an insurance company.
  • Still working with coverage from an employer with 20 or more employees? You can usually delay Part B without a penalty.
  • Most people enroll during the 7-month Initial Enrollment Period around their 65th birthday month.
Start here

Feeling lost? You are not alone

Almost everyone new to Medicare feels this way at first. There are parts with letters, and plans with letters, and the names sound alike. Part A, Part B, Part C and Part D are pieces of Medicare itself. Plan G and Plan N are types of Medigap policy. Mixing them up is completely normal.

Part APart BPart CPart D Plan GPlan N

Then the mail starts. Around your 65th birthday, letters and brochures arrive almost daily. People regularly bring a bag of it to our Chandler office, and we sort it with them: what to keep, what needs an answer, and what can go in the recycling. You are welcome to do the same.

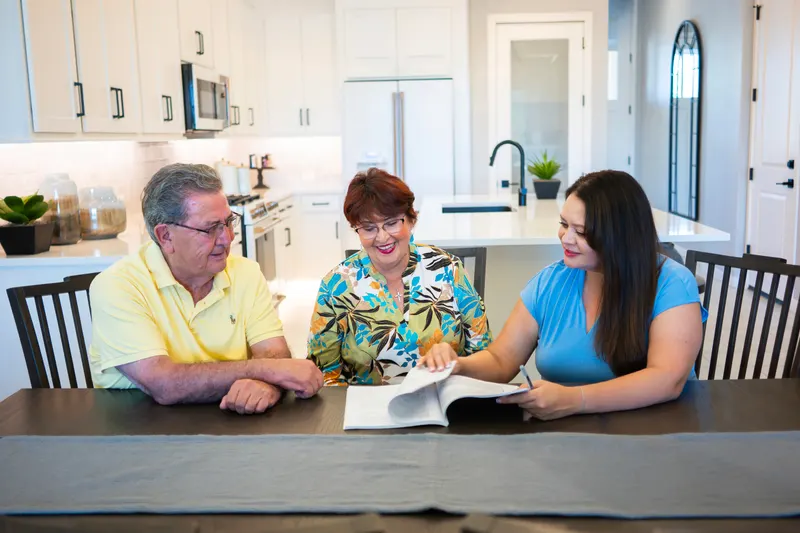
Viola Lucero reviewing a Medicare plan booklet with a retired couple at their kitchen table
Viola going through plan paperwork with clients.
Who handles what

Social Security handles only Part A and Part B

Two different doors, two different jobs. Knowing which is which saves a lot of phone calls.

Social Security

Original Medicare: Part A (hospital) and Part B (medical). This is government enrollment.

  • Apply online at ssa.gov, by phone or at a local office
  • Part B premium and any IRMAA set by Medicare
  • Delaying Part B because you are still working is handled here too
Go to ssa.gov
Medicare as your main insurance

Nine steps, in order

Retiring, or never had employer coverage? Medicare becomes your main insurance. Take it one step at a time.

  1. Step 1: Learn the basics first

    A little background makes every later decision easier: what Original Medicare pays, what deductibles and copays are, and how networks work. Our free workshops cover all of it in plain English.

    See the free Medicare workshops →

  2. Step 2: Confirm you qualify for premium-free Part A

    Most people have earned it: 40 quarters (about 10 years) of work paying Medicare taxes, yours or a spouse's. With 30 to 39 quarters, Part A costs $311 a month in 2026; with fewer than 30, $565.

  3. Step 3: Know what it will cost

    Part A is premium-free for most people. The standard Part B premium is $202.90 a month in 2026, and people with higher incomes pay more through IRMAA.

    Check whether IRMAA applies to you →

  4. Step 4: Apply through Social Security

    You can apply online at ssa.gov, by phone or at a local Social Security office. Apply about three months before the month you turn 65, so coverage can start on the first day of your birthday month.

    Sign up for Medicare at ssa.gov →

  5. Step 5: Check your red, white and blue card

    When your Medicare card arrives, make sure it shows the right start dates for Part A (hospital) and Part B (medical). Keep it somewhere safe; you will need the number to enroll in any other plan.

  6. Step 6: Choose Medigap or Medicare Advantage

    This is the big decision. A Medigap plan works alongside Original Medicare and lets you see any doctor who takes Medicare. A Medicare Advantage plan replaces it with a network plan that often adds extras. We compare both against your doctors and budget.

    Medicare Advantage vs Supplement explained →

  7. Step 7: Choose your Part D drug coverage

    If you pick Medigap, you add a separate Part D plan. Each plan lists your drugs differently, so we check your prescriptions against each one. In 2026, Part D caps what you pay for covered drugs at $2,100 for the year.

    Part D drug plans →

  8. Step 8: Keep us in your corner

    Enrolling is the start, not the end. If a claim is denied or a bill looks wrong, call us and we help sort it out, including appeals. If your Medigap rate goes up, we check whether a lower-cost plan you qualify for is available.

  9. Step 9: Review every fall

    Plans change their drug lists, copays and networks every year. During the Annual Enrollment Period, October 15 to December 7, we review your plan and prescriptions for the coming year. Right now that means 2027 plans.

    Compare 2027 plans →

Still working at 65

New to Medicare with employer coverage

Plenty of Arizonans keep working past 65. If you or your spouse have health insurance through a current job, you have a choice to make.

Keep the employer plan

If the employer has 20 or more employees, the group plan usually pays first and Medicare second. You can generally delay Part B, and its premium, without a late penalty. Many people still take premium-free Part A.

With fewer than 20 employees, Medicare usually pays first, so you generally need Part B on time.

Switch to Medicare plus a plan

Some people pay less with Medicare and a Medigap or Medicare Advantage plan than with their share of the work plan, especially once family deductibles and payroll deductions are added up.

We line up both side by side, with your doctors and prescriptions, before you decide.

Contributing to an HSA? Once any part of Medicare starts, you and your employer must stop putting money into a Health Savings Account.

Part A can be backdated up to six months when you sign up after 65, so stop contributions about six months before you apply to avoid a tax penalty. Read working past 65 and Medicare. See what your HSA saves you with the HSA tax savings calculator.

Do I need to apply?

Automatic or sign up yourself

Automatic enrollment

Already collecting Social Security (or Railroad Retirement) benefits at least four months before you turn 65? You are enrolled in Part A and Part B automatically, and your card arrives in the mail. If you are still working with employer coverage, you can choose to turn Part B down.

You apply yourself

Not taking Social Security benefits yet? Nothing happens on its own. Apply through Social Security during your Initial Enrollment Period, ideally in the three months before your birthday month.

Free tools

Work out your dates and costs

Medicare enrollment dates

See your seven-month Initial Enrollment Period, your earliest coverage date and your Medigap open enrollment window.

Part B penalty calculator

See how much a late start on Part B adds to your premium, every month, for as long as you have Part B.

IRMAA calculator

See whether your income adds a surcharge to your Part B and Part D premiums, and how much.

Turning 65 checklist

A step-by-step guide to everything to do in the months before and after your 65th birthday.

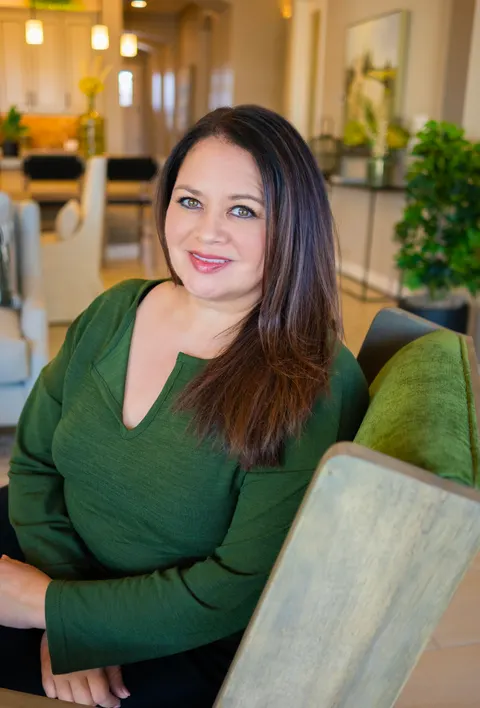
Viola Lucero, CLTC, Founder and Licensed Insurance Agent, Rise Up Benefits Group

Someone on your side: Viola Lucero, CLTC

Founder and Licensed Insurance Agent, Rise Up Benefits Group, Chandler

Viola's focus is education: making sure you know what you have, how to use it, and what it covers. We speak insurance, so you don't have to. No sales pressure, and no cost for her help.

Office hours: Monday to Friday, 9 AM to 5 PM.

In clients' words

What working with Viola looks like

★★★★★

Rise Up Benefits Group is absolutely outstanding! Viola and her team are hands down amazing. Knowledgeable, professional, and genuinely caring. They take what could be a complicated process and make it simple and easy to understand. Their expertise with Medicare enrollment gives you complete confidence in your decisions. I truly appreciate how they take the time to explain every option clearly and with patience. I highly recommend Rise Up Benefits Group to anyone needing trusted guidance with Medicare, they’re the best!

Joyce Armijo, Oct 21, 2025

Verbatim client reviews from the agency's public profiles (5.0 stars from 49 Google reviews). Read all reviews.

Free one-on-one consultation

New to Medicare? Book a one-on-one

Pick a time with Viola or a licensed agent on her team. We go through your dates, your options and your questions, by phone, by video or at the Chandler office.

  • No cost for our help
  • By phone, video or at the Chandler office
  • Your doctors and prescriptions checked first

Rather talk now? (480) 300-5776

Tell us when suits you

Send a short message with the days and times that suit you, and Viola's team will confirm a time with you personally.

Request a time

Common questions from people new to Medicare

At what age does Medicare start?

Medicare starts at 65 for most people, whether or not you have started taking Social Security. Some people qualify earlier: after 24 months of Social Security disability benefits, or with end-stage renal disease or ALS.

How do I apply for Medicare?

You apply for Part A and Part B through Social Security: online at ssa.gov, by phone, or at a local office. The online application is the quickest for most people.

Medigap, Medicare Advantage and Part D plans are separate. You enroll in those with the insurance company, and we can help you compare and apply at no cost to you.

Do I have to sign up for Medicare when I turn 65?

No, Medicare is not mandatory. But if you skip Part B and you are not covered by a current employer plan (yours or your spouse's) from an employer with 20 or more employees, you can face a late penalty: 10% added to your Part B premium for each full 12 months you went without it, for as long as you have Part B.

When is the right time to enroll in Medicare?

In the three months before your 65th birthday month. Signing up then means your coverage can start on the first day of the month you turn 65, with no gap.

Your full Initial Enrollment Period is seven months long: three months before your birthday month, that month, and three months after.

What does Medicare cost in 2026?

Part A is premium-free if you or your spouse worked about 10 years paying Medicare taxes. Otherwise it is $311 or $565 a month. The Part A hospital deductible is $1,736 per benefit period.

The standard Part B premium is $202.90 a month and the Part B deductible is $283 for the year. Single filers with income above $109,000 (or $218,000 for couples filing jointly) pay more through IRMAA. Medicare announces the 2027 amounts in the fall.

Does Medicare cover dental, vision and hearing?

Original Medicare generally does not cover routine dental care, eye exams for glasses, or hearing aids. Many Medicare Advantage plans include some of these benefits, and you can also buy a separate dental or vision plan alongside a Medigap plan.

Can I keep my employer plan when I turn 65?

Often, yes. If you or your spouse are still working and the employer has 20 or more employees, the group plan usually pays first and you can delay Part B without a penalty. With a smaller employer, Medicare usually pays first, so you generally need Part B.

Before you decide, we compare what you pay at work with Medicare plus a Medigap or Medicare Advantage plan.

What if I miss my enrollment window?

If you miss your Initial Enrollment Period and do not qualify for a Special Enrollment Period, you can sign up for Part B during the General Enrollment Period, January 1 to March 31 each year. Coverage then starts the month after you sign up, and a late penalty may apply.

If you are leaving employer coverage, you usually have 8 months after the job or coverage ends to sign up for Part B without a penalty.

Will I be enrolled in Medicare automatically?

Only if you are already collecting Social Security (or Railroad Retirement) benefits at least four months before you turn 65. Your card then arrives in the mail. If you have not started those benefits, you need to apply yourself.

Does it cost anything to work with Rise Up Benefits Group?

No. There is no cost for our help. Licensed agents are paid by the insurance company you choose, and plan premiums are the same whether you enroll with us or on your own.

Figures are 2026 amounts published by CMS. 2027 amounts are announced in the fall.

We do not offer every plan available in your area. Currently we represent 34 organizations which offer 64 products in your area. Please contact Medicare.gov, 1-800-MEDICARE, or your local State Health Insurance Program (SHIP) to get information on all of your options. Rise Up Benefits Group is not connected with or endorsed by the United States government or the federal Medicare program. Medicare has neither endorsed nor reviewed this information.

Questions about your first steps?

Book a free, no-pressure conversation with Viola in Chandler, by phone or by video.

2160 North Alma School Road, Suite 102, Chandler, AZ 85224 (480) 300-5776