
Family glitch calculator
Your job offers health insurance, but covering the family costs a lot. Check whether your spouse and children can get a Marketplace tax credit anyway.
Independent agency
Many small business owners in Chandler and across the East Valley want to offer benefits and assume they cannot afford to. In Viola's own words, she works with employers who love and care about their employees and would like to offer benefits but sometimes can't afford to. She fixes that! Her background is in business administration with an emphasis in human resources.
This is a solicitation for insurance. Submitting information or calling the numbers listed on this website will direct you to a licensed agent.
In clients' words
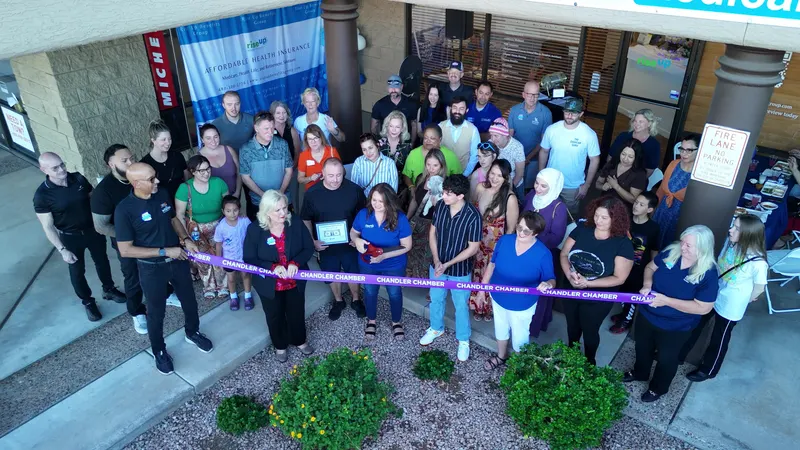
Getting insurance through Rise Up Benefits Group has been a game changer for my son and I. If you are a business owner, you need to talk to Viola. She is so kind and caring and helps you get the best plan for your health needs and budget. She takes the extra time to go over it all with you too and cares about her clients. She even hosts Client Appreciation Events and it makes you feel valued. I highly recommend this company in every way.
Verbatim client reviews from the agency's public profiles (5.0 stars from 49 Google reviews). Read all reviews.
Group benefits are not all or nothing. A small employer can start with one piece, such as a group health plan, or with lower cost benefits like dental, vision, life or supplemental coverage that employees value, and build from there. Viola lays out what a starter package and a fuller package would cost, so you choose with real numbers.
Group health plans have their own rules: participation and contribution requirements set by the insurance company, waiting periods for new hires, and renewals each year. Some employers prefer to contribute to employees' individual coverage instead of buying a group plan; there are specific arrangements for that, with their own rules, and Viola explains when they may fit.
Voluntary benefits are a useful tool. Dental, vision, life, critical illness, hospital indemnity and short-term care can be offered so employees choose and pay for what they want through payroll deduction. That gives your team access to group coverage while keeping your own costs predictable.
Then comes the part most brokers skip: education. Viola explains the benefits to your employees in plain language, at enrollment and afterwards, so they know what they have, how to use it and what it covers. Fewer confused employees means fewer questions landing on the owner's desk.
She stays with you through the year: adding new hires, handling changes, helping employees with claims questions, and reviewing every renewal so you are not simply accepting an increase. When someone leaves, she can help them compare COBRA with an individual plan.
You run a small business in Chandler or the East Valley, you care about your employees, and you want to offer benefits that help you hire and keep good people without breaking the budget.
Often more than owners expect. You can start small, with one benefit or voluntary coverage your employees pay for through payroll, and grow over time. Viola prices a few options side by side so you can see what fits before you commit.
Free calculators for this coverage. Results are estimates, not quotes.
Your job offers health insurance, but covering the family costs a lot. Check whether your spouse and children can get a Marketplace tax credit anyway.
See how much tax a Health Savings Account contribution could save you in 2026, within the IRS limits.
If you are under 65 and do not have coverage through work, you have more choices than most people realize. Here is a plain English map of each one for Chandler and East Valley families, what it costs you, and what it leaves out.
Leaving a job means choosing between keeping your old plan through COBRA or switching to a Marketplace plan. Here is how to compare them, what the deadlines are, and when each one makes sense.
How HealthCare.gov works in Arizona: who can enroll, the 2027 Open Enrollment dates, what the metal levels really mean, and the out-of-pocket limits that cap a bad year.
Often more than owners expect. You can start small, with one benefit or voluntary coverage your employees pay for through payroll, and grow over time. Viola prices a few options side by side so you can see what fits before you commit.
Small group plans are generally available to businesses with at least one employee other than the owner and spouse, though insurance companies set participation and contribution requirements. Viola explains the rules for the plans she offers.
Coverage like dental, vision, life, critical illness or hospital indemnity that employees choose and pay for through payroll deduction. Employers can offer them at little or no cost to the business.
Yes, through specific reimbursement arrangements with their own rules about eligibility and notices. Viola can explain whether that approach or a group plan fits your business better.
The insurance company sets new rates and may change plan options. Viola reviews the renewal with you, compares alternatives, and helps you decide whether to keep, adjust or change plans.
Not if you are a small business. The federal employer requirement applies to employers with 50 or more full-time employees, including full-time equivalents. Arizona does not add its own requirement for smaller employers.
Many small businesses still offer benefits to hire and keep good people. Viola can show you what a starter package might look like for your team.
There can be. The Small Business Health Care Tax Credit is for employers with fewer than 25 full-time equivalent employees and average wages under a yearly limit. You must pay at least half of employee-only premiums and buy coverage through the SHOP Marketplace.
The credit can be claimed for two consecutive years. Ask your tax advisor whether you qualify, and Viola can explain the plan side.
Generally any time of year. Insurance companies may require a minimum share of employees to enroll and a minimum employer contribution.
Each year from November 15 to December 15, small employers can start a plan even if they do not meet those participation or contribution requirements. Viola can tell you whether that window helps your business.
Usually, yes. Most group health plans let employees add a spouse and children, and children can stay on a parent's plan until age 26. You decide how much, if anything, the business contributes toward family coverage.
Viola prices employee-only and family options side by side, so you can set a contribution that fits your budget.
Employer Group Benefits in Chandler and across Arizona: no pressure, plain answers, and a review every year.
2160 North Alma School Road, Suite 102, Chandler, AZ 85224 (480) 300-5776
Your choices are saved on this device.